A finance structure that ignores how your business earns can squeeze cash flow for years. We help businesses fund vehicles, trucks, yellow goods and equipment through chattel mortgages, finance leases and hire purchase. Repayments, term and any balloon are set to match the income the asset will bring in.
Who it suits
Tradies, sole traders, owner-drivers, transport and civil operators, farmers, and established businesses Australia wide.
Common purposes
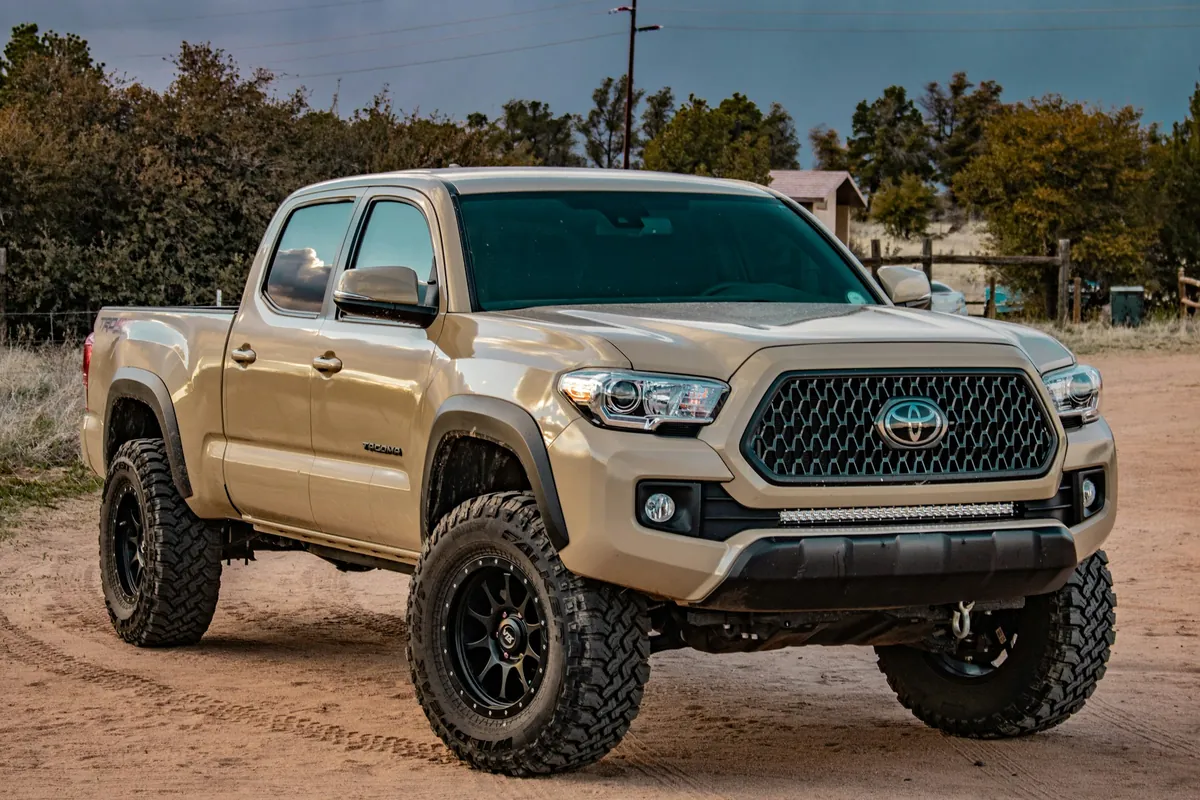
- Cars, utes and vans for business use
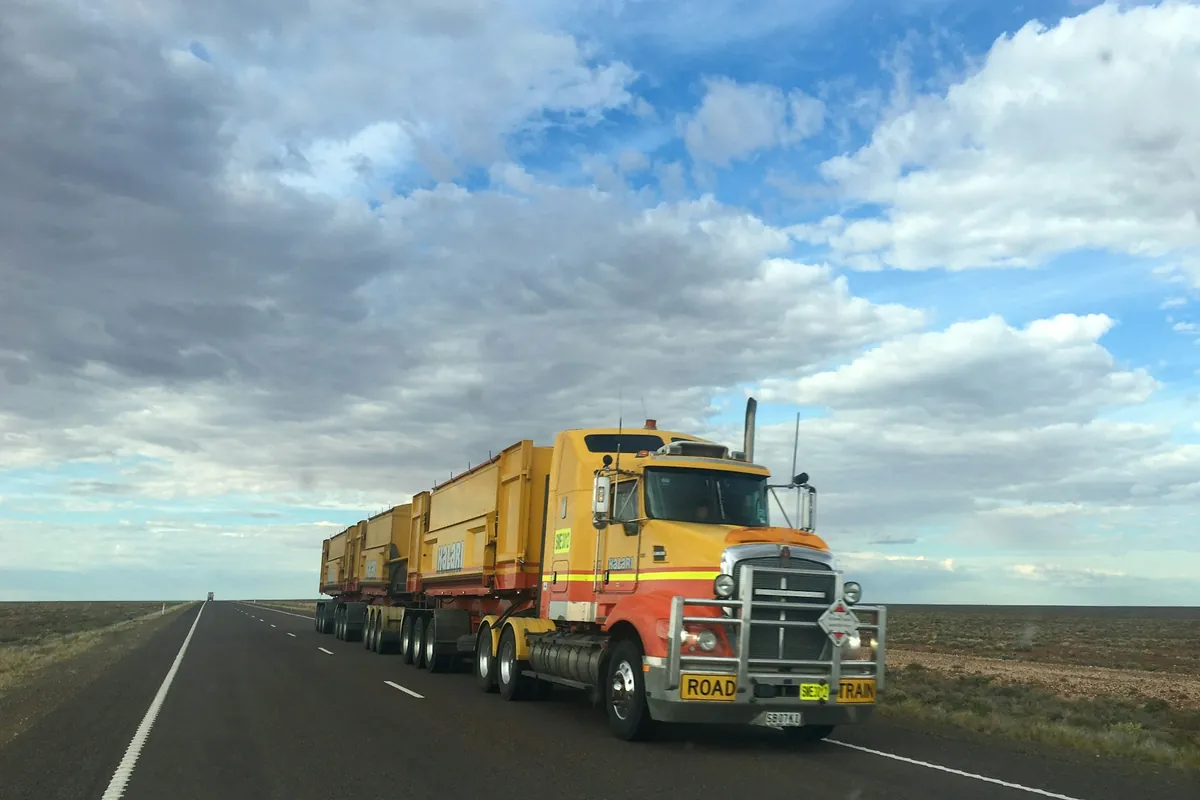
- Trucks, prime movers and trailers
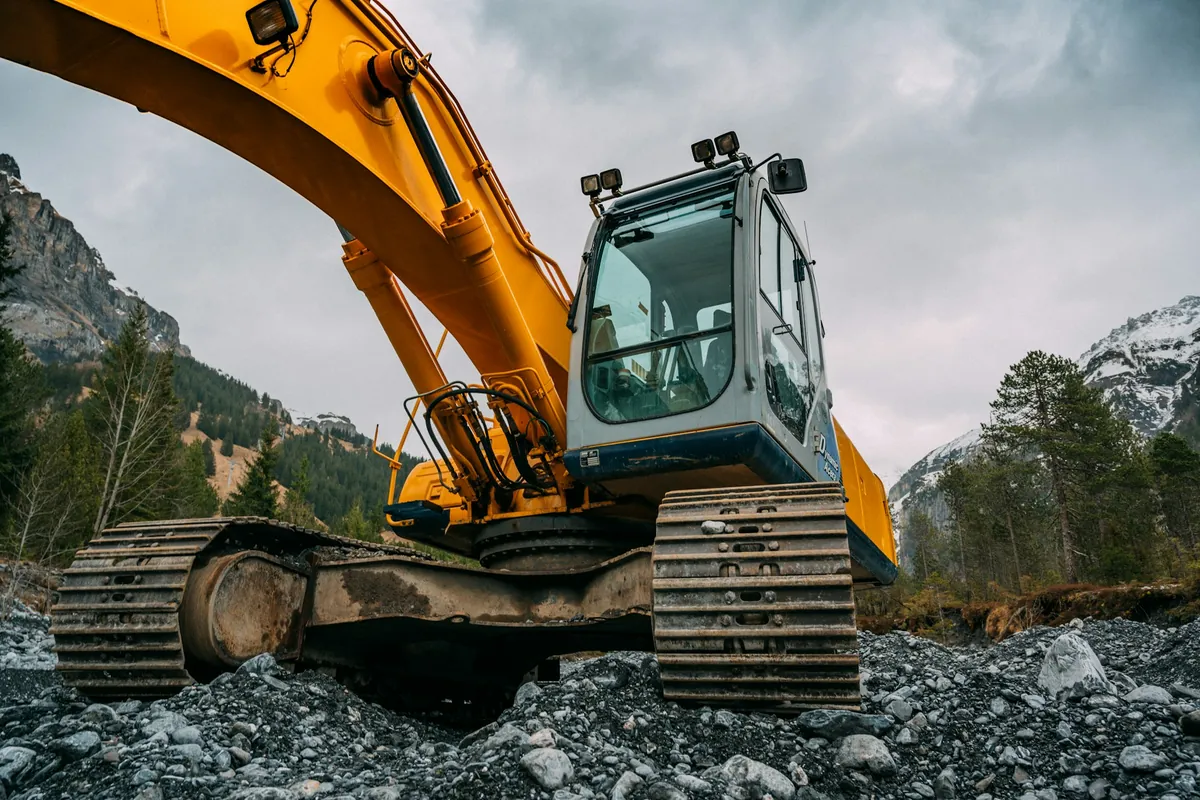
- Excavators, machinery, yellow goods and specialist equipment
What we work through with you
- Asset type, age and condition, and how it will be used
- Trading history, cash flow and existing commitments
- Deposit, term, repayment structure and any balloon or residual
Documents to have ready
- ABN and business details
- Supplier quote or tax invoice
- Photo identification
- Financials or bank statements, depending on the lender and loan size
How we work
We start with a conversation about what you are trying to achieve and your timing. We then gather the information lenders will ask for and assess suitable options from our approved lender panel and relevant specialist channels. Before anything is lodged, you will know the costs, the trade-offs and why we are recommending an option. After that, we manage the application through to settlement.
What is asset and equipment finance?
Asset finance lets an eligible business put a vehicle, truck, machine or piece of equipment to work now and pay for it over an agreed term, usually with the asset itself as security. That can keep working capital free for wages, materials and growth. The structures available depend on the asset, how it will be used, your financial position and lender policy.
Common business finance structures
| Structure | General ownership position | Points to consider |
|---|---|---|
| Chattel mortgage | The business generally owns the asset from settlement and the lender takes security over it. | Loan term, interest, fees, deposit and any balloon payment. |
| Finance lease | The financier owns the asset and leases it to the business for agreed payments. | End-of-term options, residual value, total cost and usage conditions. |
| Commercial hire purchase | The financier generally owns the asset until the final payment, when ownership transfers. | Deposit, term, payment schedule and final ownership conditions. |
What we can help finance
Subject to lender criteria: business cars, utes and vans; trucks, prime movers and trailers; excavators, loaders and other yellow goods; tractors and farm machinery; medical and dental equipment; commercial kitchens; and most other equipment that earns income for your business. New or used, from a dealer or, in many cases, a private seller.
What lenders look at
Expect questions about your ABN and how long you have traded, your industry experience, business cash flow and existing debts, and the asset itself: its age, condition, supplier and the work it will do. Streamlined and low-doc options exist for many ABN holders, but they still involve lender assessment and verification. We tell you up front what your application is likely to need, so there are no surprises halfway through.
Adelaide-based, working Australia wide
Our office is in Vale Park, Adelaide, and we finance assets for businesses in every state and territory. Quotes, documents and signatures can all be handled electronically, so a tipper in Townsville or an excavator in the Pilbara goes through the same process as a ute in Adelaide.